
Europe-low penetration rate and high growth space
Under the European energy crisis, the high economics of European household optical storage has been recognized by the market, and the demand for optical storage has opened up explosive growth. The implementation of residential electricity price contract mechanism, 2023 new contract electricity prices rose significantly, the average price of electricity for more than 40 euros / MWh, an increase of 80-120% year-on-year, is expected to continue to maintain high prices in the next 1-2 years, the rigid demand for optical storage clear.
Germany exempted from household photovoltaic VAT, income tax, Italy household storage subsidies policy slope back, favorable policies continue, Germany household storage yield up to 18.3%, the subsidy payback period can be shortened to 7-8 years. Long-term independent energy has become a major trend, 2021 European household storage penetration rate of only 1.3%, a broad space for growth, commercial and industrial and large storage market is also growing rapidly. It is estimated that in 2023/2025, the new capacity demand for energy storage in Europe is 30GWh/104GWh, with 113% increase in 2023 and CAGR=93.8% in 2022-2025.
US-ITC policy encouragement
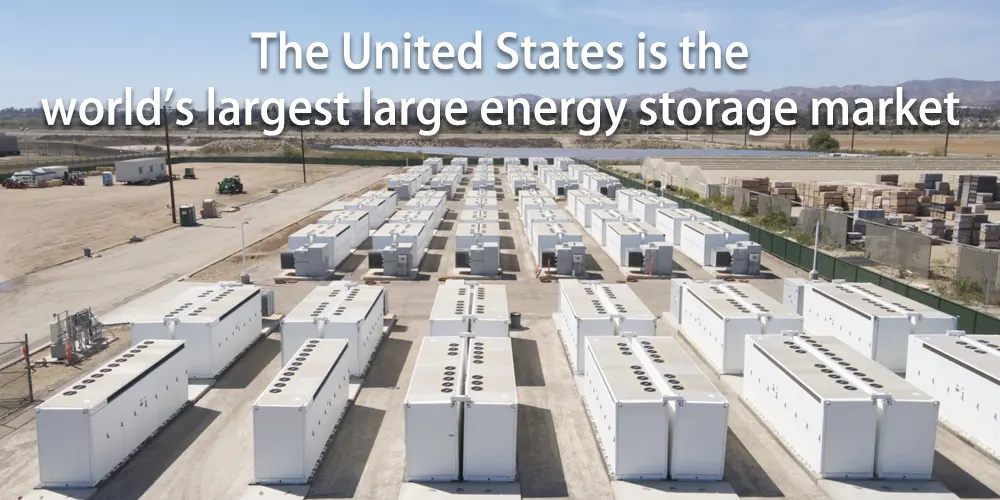
The United States is the world’s largest large energy storage market, 2022 1-3 quarter U.S. energy storage installed 3.57GW/10.67GWh, up 102%/93% year-on-year. As of November, the volume of filings has reached 22.5GW, 2022 PV new installations to slow down, but energy storage still maintain high growth. 2023 PV installation to the good, overlapping with the storage penetration rate continues to rise, supporting the continued explosion of energy storage installations.
Poor coordination among U.S. power suppliers, energy storage with regulatory utility value, full opening of auxiliary services, high degree of marketization, high PPA tariff with storage premium is obvious. ITC tax credit extended for 10 years and increase the credit ratio to 30%-70%, for the first time the independent energy storage into the subsidy, to promote a significant increase in yield. Estimated 2023/2025 U.S. energy storage new capacity demand for 36/111GWh, respectively, with a 117% increase in 2023, 2022-2025 CAGR = 88.5%.
China-high growth in demand under the policy
China’s 2022 1-3 quarter installed capacity reached 0.93GW/1.91GWh, the structure of large energy storage accounted for more than 93%, 2023 ground PV start + storage penetration rate, high growth in installed demand, according to incomplete statistics, 2022 energy storage public bidding amounted to 41.6GWh. shared energy storage model is spreading rapidly, capacity compensation, power spot market, time-sharing The shared energy storage model is spreading rapidly, and capacity compensation, power spot market, time share mechanism, etc. are gradually coming into place to improve the yield of energy storage. China’s new energy storage capacity demand is estimated to be 33/118GWh in 2023/2025, with 205% year-on-year growth in 2023 and CAGR=122.2% from 2022-2025.
New technologies such as sodium ion battery, liquid flow battery, photothermal energy storage and gravity energy storage are being landed and are gradually evidenced at the bidding end. Strengthened energy storage safety management, high voltage cascade, liquid cooling system, Pack fire penetration gradually increased. Energy storage battery shipments are clearly differentiated, inverter companies to enter the PCS with advantages.
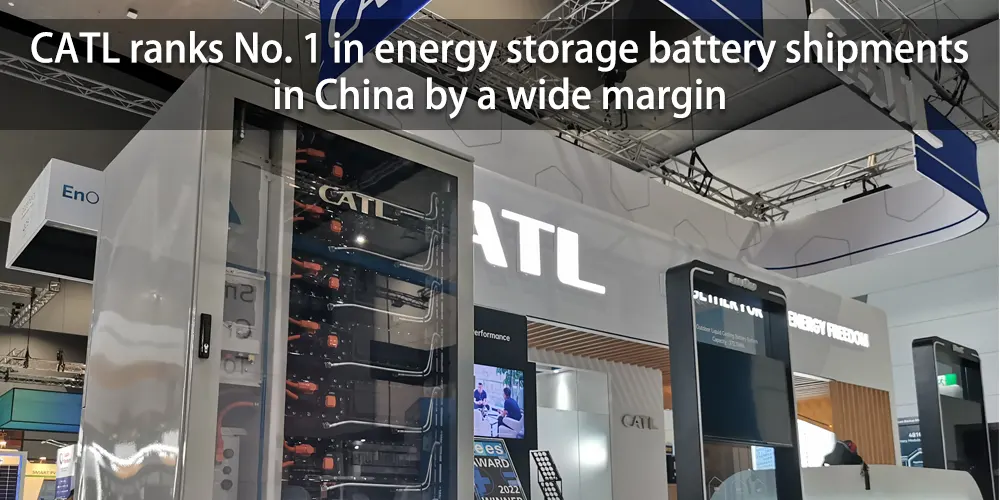
CATL ranked first among Chinese energy storage battery manufacturers in terms of shipment volume with an absolute advantage. 2021 global energy storage battery shipment volume ranked top 10 Chinese companies, CATL’s shipment volume is about 16GWh, far ahead of peer companies ranked first, Great power’s shipment volume is about 3GWh, with a slight advantage over BYD ranked second. Among them, CATL focuses on the large energy storage market, Great power leads in the household storage market, while BYD and EVE focus on both.
Sungrow is No.1 in China for energy storage PCS shipments, with obvious first-mover advantage. Since energy storage PCS is homologous with PV inverter technology, most of the leading companies of energy storage PCS are PV inverter manufacturers. sungrow cut into energy storage PCS from PV inverter field, and ranked No.1 with about 2.5GW shipment in 2021, which has obvious first mover advantage.
Summary
Thanks to the explosion of large-scale energy storage in China and the U.S. and household storage in Europe, global energy storage capacity demand is expected to be 120/402 GWh in 2023/2025, with a year-on-year growth of 134% in 2023 and a CAGR of 98.8% from 2022-2025.
On the supply side, new entrants to the energy storage industry are emerging. The pattern of electric core is more concentrated, CATL shipments of the world’s first, BYD and EVE and other companies to maintain high growth in shipments; energy storage inverter focus on the channel and brand services, the pattern of concentration, Sungrow is strong in IGBT supply assurance ability, in the large energy storage market firmly in the leading, household storage inverter growth rate is high, household storage leading companies shipments of several times in a row.
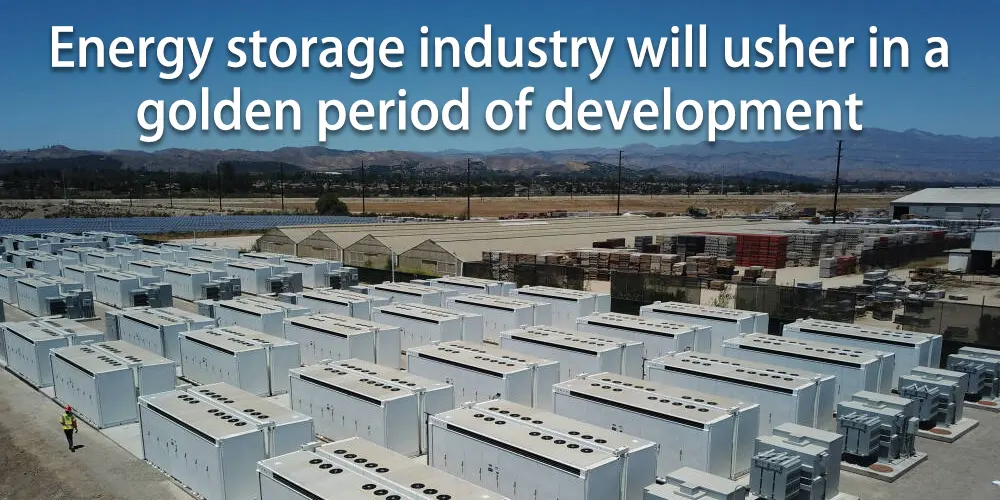
Under the accelerated energy transition, the cost of photovoltaic ground power plants will fall in 2023 and will usher in the peak of installation, accelerating the outbreak of large energy storage market in China and the United States; household storage will explode in Europe in 2022 and will still keep doubling in 2023, and household storage will also become a mainstream trend in emerging regions such as the United States and Southeast Asia, and the energy storage industry will usher in a golden development period.

 English
 French
 German